 01206 544333
Investing in a House in Multiple Occupation can offer attractive rental opportunities, but an HMO also comes with additional planning, licensing, safety and management considerations.
Before buying, refinancing or converting a property into an HMO, investors need to look beyond the headline rental income. The planning position, licence requirements, mortgage eligibility, ongoing costs and condition of the property can all influence whether the investment is viable.
Our downloadable HMO Investor Checklist provides a practical starting point for assessing an HMO opportunity and identifying the important checks that should be completed before you proceed.
Download the HMO Investor Checklist
Use our practical checklist to review the property, finance, licensing, safety and management considerations associated with an HMO investment.👉🏼 HMO CHECKLIST 📋
.
What Should You Check Before Buying an HMO?
Before committing to a purchase, it is important to understand the local rental market and how the property is currently being used.
Start by researching demand for rooms in the area and the level of rent comparable properties are achieving. Your calculations should allow for void periods, running costs and any refurbishment or conversion work that may be required.
You should also check:
- Whether the property is already operating as an HMO
- Its current planning use class
- Whether it is located within an Article 4 area
- Any planning restrictions or conditions
- Whether an existing HMO licence is in place
- The property’s current EPC rating
- Whether the proposed mortgage is suitable and affordable
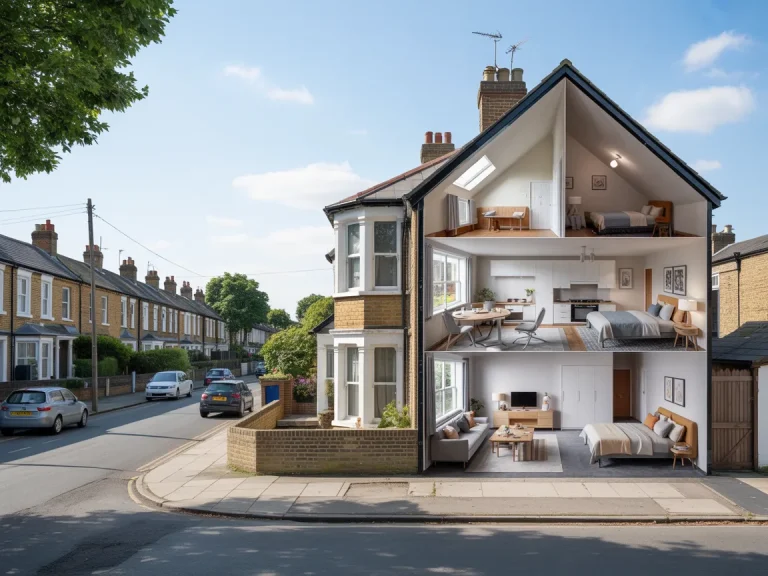
Planning use may fall under C3, C4 or Sui Generis, depending on how the property is occupied and its size. The correct position should always be confirmed before committing to the purchase or conversion.
.
HMO Licensing and Compliance
Licensing requirements can vary between local authorities. An investor should confirm whether mandatory HMO licensing applies and whether the council operates any additional or selective licensing schemes.
The local authority may have specific requirements covering:
- The number of permitted occupants and households
- Minimum bedroom sizes
- Kitchen, bathroom and toilet facilities
- Waste storage and collection
- Property management arrangements
- Licence conditions
- Inspections and certificate renewals
It is also important to remember that HMO licensing and planning permission are separate requirements. Having a licence does not automatically confirm that the property has the correct planning use, and having planning consent does not remove the need to check licensing requirements.
.
Fire and Property Safety
Fire safety is a major consideration when buying or operating an HMO. The requirements will depend on the property, its layout, the number of occupants and the relevant local authority standards.
Checks may include:
- Suitable smoke alarms and heat detectors
- Carbon monoxide alarms where required
- Compliant fire doors
- Clear and properly maintained escape routes
- Emergency lighting
- Fire-fighting equipment
- Annual gas safety checks
- A valid Electrical Installation Condition Report
- Portable appliance testing where appropriate
Landlords should keep organised records of inspections, safety certificates and any remedial work completed at the property.
.
Arranging Finance for an HMO
HMO finance is more specialist than a standard residential buy-to-let mortgage. Lenders may consider the property layout, number of lettable rooms, rental income, licensing position and the applicant’s experience.
Before applying, investors should review:
- Specialist HMO mortgage options
- Interest-only and capital repayment structures
- The lender’s rental stress-test requirements
- Valuation, legal and broker costs
- Licensing and compliance expenditure
- The cost of utilities included within the rent
- Specialist HMO landlord insurance
- Contingency funds for repairs, voids and unexpected costs
The finance arrangement should support both the immediate purchase and the longer-term strategy. If works or conversion are planned, it may also be necessary to consider how the property will be refinanced once they are complete.
.
Budgeting for Ongoing Management
An HMO can experience greater wear and tear than a standard single-tenancy property, particularly in kitchens, bathrooms and communal areas.
A realistic budget should allow for:
- Regular property inspections
- Repairs and safety-related work
- Cleaning and gardening
- Decoration and furniture replacement
- Appliance repairs and replacement
- Maintenance of communal areas
- Tenancy and deposit administration
- Licence and certificate renewals
Investors should also decide whether the property will be managed directly or through a suitable managing agent. Keeping tenancy, deposit, inspection and compliance records organised can make the property easier to manage and help reduce the risk of important renewal dates being missed.
.
Making the Property Attractive to Tenants
Compliance is essential, but the property must also meet the expectations of the local tenant market.
Depending on the location and target tenant, this could include:
- Competitively priced rooms
- Reliable high-speed broadband
- Well-maintained furniture and decoration
- Good-quality communal areas
- Usable work-from-home space
- En-suite facilities where practical
- Clear and reasonable house rules
Investors should compare the property with competing HMOs in the area and consider which improvements might support tenant demand and retention. Utility usage and costs should also be reviewed regularly, particularly where bills are included within the rent.
.
Five Key Checks Before You Commit
Although every HMO investment is different, there are five areas that should be checked before committing:
- Planning permission
- Licensing
- Fire safety
- Mortgage eligibility
- Insurance
These checks can help identify potential issues before contracts are exchanged or significant money is spent on refurbishment and conversion work.
.
Download the HMO Investor Checklist
Our downloadable checklist brings the main considerations together in one practical document.
Use it as an initial guide when assessing an HMO purchase, refinance or conversion. Requirements can vary depending on the property and local authority, so the position should always be verified with the relevant council and suitably qualified professionals.
👉🏼 HMO CHECKLIST 📋
.
How can Advocate Finance help?
HMO mortgage applications can be more involved than standard buy-to-let cases, particularly where the property requires conversion work, has an unusual layout or is subject to specific planning and licensing requirements.
We can help you explore suitable HMO mortgage, refinancing and property conversion finance options.
If you are considering buying, converting or refinancing an HMO, contact us for a free initial assessment.
We provide a FREE assessment on all our services.
Please contact us directly for more information, or use the Get in Touch With Us Today feature at the bottom of this page.