 01206 544333
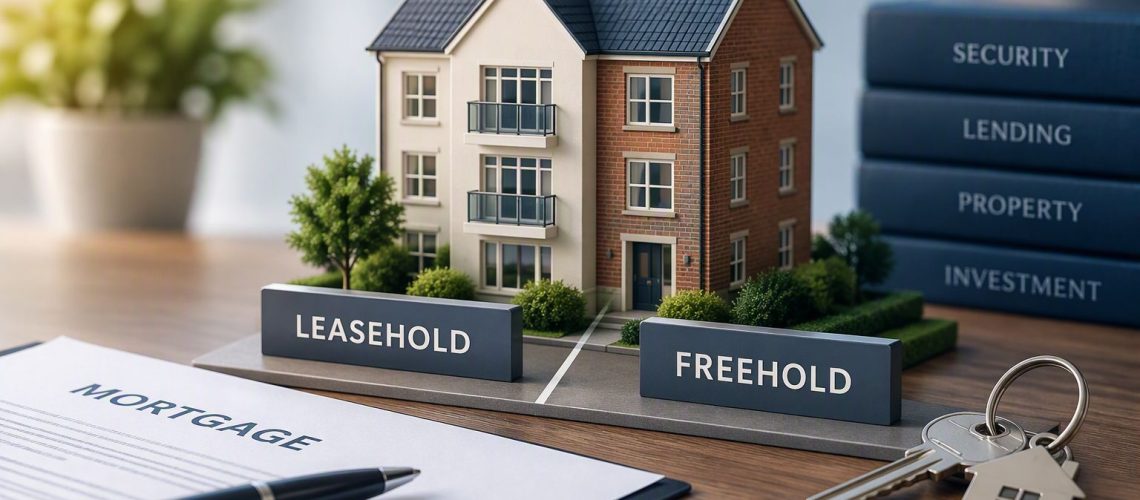
If you are a property investor looking to finance an individual leasehold property, you may come across a requirement that is not always obvious at the outset: a comfort charge over the freehold title.
This is typically required where you own both the leasehold interest in the property you are looking to finance and also the freehold interest in the building or wider property.
So, why might a mortgage lender ask for additional security over a freehold that you already own?
.
What is a Comfort Charge?
A comfort charge is a form of additional security that a lender may require over the freehold title, alongside its main first legal charge over the individual leasehold title.
The precise requirements will depend on the lender and the legal structure of the transaction. However, where the borrower owns or has a connection to both the leasehold and freehold interests, the lender may want protection over both titles.
The reason this is required, is to protect the lender’s position and ensuring that the leasehold property can be sold if the lender ever needed to repossess the property.
.
Why does owning the Freehold Matter?
Imagine you own a building containing several flats. Each flat has been granted its own individual leasehold title, and you also own the freehold of the building.
You now want to raise a buy-to-let mortgage against one of those leasehold titles.
The lender will typically take a first legal charge over the leasehold title being financed. However, because you also own the freehold, the lender may consider whether your control of the freehold could affect its ability to sell the leasehold property if the mortgage falls into arrears and repossession becomes necessary.
This is where the comfort charge may come into play.
.
How could the Freeholder Delay a sale following repossession?
A key consideration for mortgage lenders is the ability to enforce a sale if a borrower defaults on their mortgage.
If a lender repossesses a leasehold property, the property may need to be marketed and sold to recover the outstanding mortgage debt.
During the sale process, the buyer’s solicitor may raise enquiries relating to the lease, the freeholder, the management arrangements, service charges, ground rent, insurance and other matters affecting the property.
Where the borrower also owns the freehold, the lender may be concerned that responses to freeholder enquiries could be delayed if the former borrower is uncooperative, unavailable or unwilling to assist.
For example, if the lender needs information or documentation from the freeholder to progress a sale, any delay in obtaining it could slow down the conveyancing process. This could make the property more difficult to sell promptly and potentially increase the lender’s costs.
The concern is therefore not simply about the borrower’s ownership of the freehold. It is about whether the lender can deal with the leasehold property effectively and protect its position in the event of a repossession.
.
How can a Comfort Charge help?
Depending on the lender’s requirements and the legal documentation, a comfort charge can provide additional security over the freehold interest.
This is intended to strengthen the lender’s position where the freehold and leasehold ownership are connected, rather than leaving the lender reliant solely on its security over the individual leasehold title.
It is important to understand that the exact effect of the charge depends on its terms. It should not be assumed that a comfort charge automatically gives a lender unrestricted control over the freehold or guarantees that every potential conveyancing delay will be avoided.
The lender’s solicitor will need to confirm the appropriate legal structure and any additional consents or requirements.
.
Is a Comfort Charge always required?
No. A comfort charge is not an automatic requirement for every leasehold mortgage.
Lenders have different lending criteria, and their requirements can depend on factors such as:
- Whether the borrower owns the freehold as well as the leasehold.
- Whether the freehold and leasehold are held by the same individual or by connected companies.
- The structure of the building and the number of individual leasehold titles.
- Whether the freehold is already mortgaged or subject to another lender’s security.
- The lender’s approach to protecting its security and ensuring the property remains marketable.
Some lenders may be willing to proceed without a comfort charge, while others may insist on additional security where the ownership interests are connected.
This is why understanding the ownership structure before submitting a mortgage application is important.
.
.
How can Advocate Finance help?
We understand that property ownership structures can sometimes make securing finance more complex. Whether you own both the freehold and leasehold interests or are unsure whether a comfort charge will be required, please get in touch and we can help you understand your options.
We provide a FREE assessment on all our services.
Please contact me directly for more information, or use the Get in Touch With Us Today feature at the bottom of this page.