 01206 544333
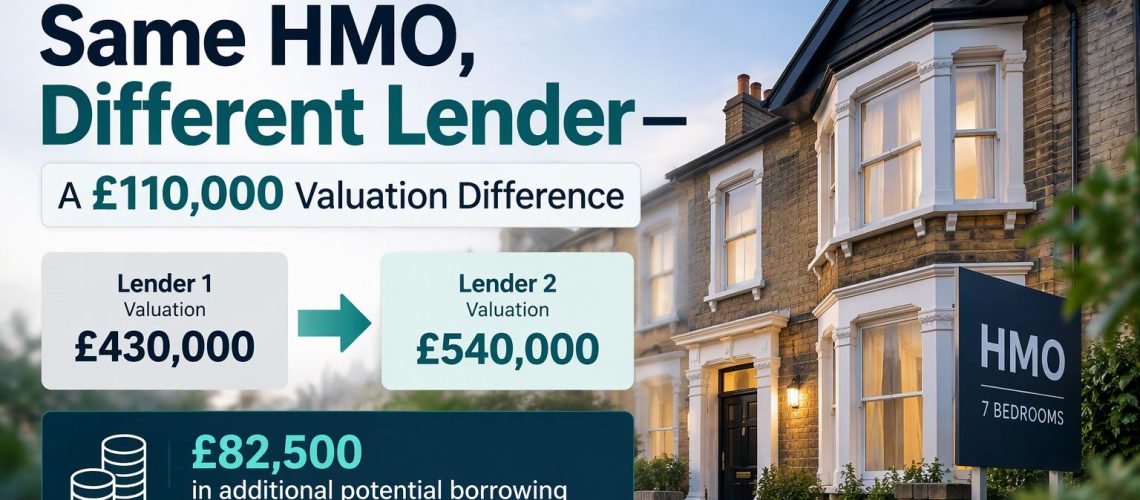
By carefully considering different lenders’ approaches to HMO valuations, we helped a pair of property investors achieve a £540,000 valuation – £110,000 above the initial assessment. At 75% loan-to-value (LTV), this represented £82,500 in additional potential borrowing.
.
The Client’s Situation
Two experienced property investors approached us to refinance a recently converted and refurbished seven-bedroom HMO.
With annual rental income of £69,120, they estimated the property’s value at £540,000. Their aim was to release funds for further investment while securing competitive borrowing costs.
Although experienced landlords, they were unfamiliar with how different lenders approach HMO valuations and wanted specialist guidance.
.
The Challenge
For these clients, the interest rate was only part of the decision. The valuation would also determine how much they could borrow and reinvest in their portfolio.
One competitively priced lender offered a free valuation, but our experience suggested its assessments could be conservative. An alternative lender offered a valuation approach we felt could better support the clients’ objectives, although its borrowing costs were slightly higher.
The challenge was to explore the lower-cost option without losing sight of the clients’ need to release sufficient funds.
.
Our Approach
The clients had not been through the commercial HMO valuation process before. They were understandably reluctant to commit to a more expensive mortgage product and a paid valuation without first exploring the competitively priced lender offering a free valuation.
A higher valuation from an alternative lender was possible, but not guaranteed. Equally, the lower-cost lender could still return a valuation that met their needs. Skipping this option entirely could leave the clients wondering whether they were paying more unnecessarily.
We therefore explained and agreed a two-stage plan before submitting an application.
Plan A: Explore the lower-cost option.
For a £299 application fee, the clients could obtain the first lender’s free valuation. If it supported their borrowing requirements, they could proceed with competitive pricing without needing to explore a more expensive alternative.
We made clear that, based on our experience, the valuation could fall below their expectations. The clients understood that the £299 could become an additional cost if they needed to move to Plan B.
Plan B: Use an alternative lender if needed.
If the first valuation was insufficient, we would approach a lender with whom we had stronger experience of commercial HMO valuations. This would involve a paid valuation and slightly higher borrowing costs, with no guarantee of a higher assessment.
Explaining both routes upfront gave the clients a clear understanding of the costs, uncertainties and decisions involved. They knew what a satisfactory valuation would mean, what would happen if it fell short, and why an alternative lender might still be worth considering.
.
The Result
The first lender valued the property at £430,000, below the clients’ expectations. While disappointing, this was an outcome we had discussed from the outset, and the clients already understood the next step.
We put Plan B into action, securing a valuation of £540,000. The £110,000 difference represented £82,500 in additional potential borrowing at 75% LTV.
Having explored both options, the clients could make an informed decision. They chose the higher valuation despite the slightly higher borrowing costs, as the additional borrowing capacity better supported their plans to recover capital invested in the refurbishment and fund future investments.
The structured approach also gave them peace of mind: they had tested the lower-cost option before committing to the alternative, understood the risks throughout, and had a clear plan to follow at each stage.
.
.
How can Advocate Finance help?
A successful HMO refinance means balancing borrowing costs, valuation and your investment goals. Understanding how lenders approach your property—and explaining the options clearly from the outset—can make a significant difference.
If you’re refinancing an HMO, speak to our team about structuring the finance around your property and your plans.
We provide a FREE assessment on all our services.
Please contact me directly for more information, or use the Get in Touch With Us Today feature at the bottom of this page.